Table of Contents
Imagine telling an AI assistant: “Keep my monthly software subscriptions under ₹5,000, replace anything that expires, and choose the cheapest suitable option.”
You go to sleep.
The AI searches, compares products, checks prices, places an order, and pays—without asking you to approve every individual transaction.
That sounds convenient. It also creates an uncomfortable question: how much authority should an AI have over your money?
This is where AI agent spending limits become important. Instead of giving an AI unrestricted access to a credit card or bank account, emerging payment systems are being designed around permissions, authentication, transaction limits, tokens and approval rules.
The technology is moving quickly. But the real challenge is not teaching AI how to pay. It is teaching financial infrastructure exactly when an AI is allowed to pay—and when it must stop.
Why AI agents need spending limits
Traditional online shopping assumes a human is sitting somewhere between intention and payment.
You select the product, enter payment details, check the total and press “Buy.”
An autonomous AI agent changes that sequence.
The agent could potentially:
- Search for products or services
- Compare prices
- Negotiate or select an option
- Place an order
- Schedule recurring purchases
- Pay another service automatically
- Make many transactions in succession
That creates a fundamental need for AI agent spending limits.
Suppose you tell an agent to purchase office supplies whenever inventory falls below a certain level. Without boundaries, a mistake in its interpretation could produce an unexpectedly large order.
A spending limit can become one layer of protection between an AI’s decision and your bank balance.
Visa’s current agentic-commerce infrastructure describes controls such as spending limits, approval thresholds, authentication and other permission layers as part of keeping consumers in control.
AI agents probably won’t use your credit card like a human
So, can AI agents use credit cards directly?
Not necessarily in the way a person does.
The emerging model is closer to giving an agent a controlled payment credential or token rather than handing it unrestricted access to your underlying card information.
For example, a payment system could theoretically authorize an agent to spend up to a defined amount with a particular merchant or within a particular category.
OpenAI’s Agentic Commerce Protocol already illustrates this approach. Its current Instant Checkout implementation uses encrypted payment tokens that are authorized for specific amounts and merchants, while the user explicitly confirms the purchase.
This is an important distinction.
The AI does not necessarily receive the equivalent of your physical wallet. Instead, the payment infrastructure can determine what the agent is allowed to do.
That is the basic idea behind AI agent spending limits.
What could an AI spending permission actually look like?
The most useful way to understand AI agent spending limits is to think of them as a permission system.
Instead of saying:
“AI, you can spend my money.”
You might eventually say:
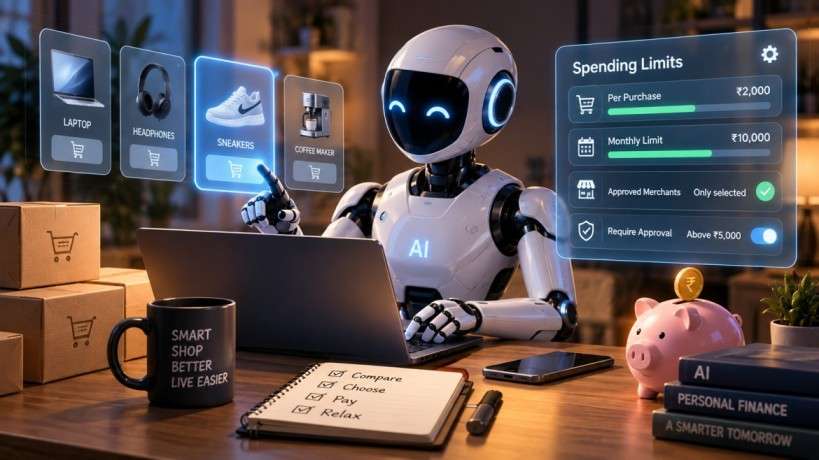
“AI, you can spend up to ₹2,000 per purchase, ₹10,000 per month, only with approved merchants, and anything above ₹5,000 requires my confirmation.”
That creates several possible controls.
Transaction limits
A maximum amount can be attached to an individual purchase.
Daily or monthly budgets
The agent could receive a fixed spending allowance over a defined period.
Merchant restrictions
The permission could apply only to certain merchants or categories.
Approval thresholds
Small purchases might happen automatically while larger purchases require human confirmation.
Purpose restrictions
An agent could be authorized for groceries, travel or business software but not unrelated purchases.
These layers could make AI agent spending limits more flexible than simply turning autonomous payments on or off.
What is agentic commerce?
Agentic commerce describes transactions in which AI agents participate in discovering, deciding about and completing purchases on behalf of people or organizations.
The important change is that the AI becomes an active participant rather than merely a recommendation tool.
OpenAI’s Agentic Commerce Protocol, developed with Stripe, is one example of infrastructure designed to let AI agents, consumers and businesses communicate during a purchase. The protocol is intended to work with different platforms and payment processors while allowing merchants to retain control of fulfillment and customer relationships.
Visa similarly describes an agentic commerce protocol as a standardized way for agents, merchants and platforms to communicate and transact securely.
In simple terms, it is a common language for automated buying.
What is the Agentic Commerce Protocol?
If you are asking what is the agentic commerce protocol, there is an important distinction: there is not necessarily one universal protocol controlling all AI commerce.
Different companies and organizations are developing standards and infrastructure for different parts of the process.
OpenAI and Stripe’s Agentic Commerce Protocol focuses on connecting AI agents, people and businesses for commerce. Meanwhile, Visa and Mastercard are developing their own infrastructure and standards for trusted agent interactions and payments.
The goal across these efforts is similar:
An AI should be identifiable, authorized and constrained when it handles a transaction.
That makes AI agent spending limits part of a larger authorization system rather than a simple number attached to a card.
Where do virtual cards for AI fit?
Another approach involves virtual cards for AI.
Virtual cards can provide payment credentials that are separate from a user’s primary physical card. In an agentic system, the credential could potentially be restricted according to the rules established by the user, financial institution or payment platform.
Imagine creating a virtual payment credential specifically for an AI travel assistant.
You could potentially configure it for:
- Flights and hotels
- A specific trip
- A defined budget
- A limited validity period
- Additional approval for expensive purchases
The exact capabilities depend on the payment provider and implementation, but the concept is straightforward: separate the agent’s payment authority from unrestricted access to your primary financial credentials.
This is another reason AI agent spending limits are likely to become a core part of autonomous commerce.
The Machine Payments Protocol changes the picture
Consumer shopping is only one side of the story.
AI agents may also purchase digital services from other software systems. An agent could need cloud computing, API calls, data access or other machine-readable services.
This is where the Machine Payments Protocol, or MPP, becomes relevant.
Stripe and Tempo introduced MPP as an open standard for machine-to-machine payments, while Visa announced support for card-based payments through the protocol in 2026. Visa described potential uses including API calls, cloud resources and machine-to-machine services.
This could create a world where software does not simply purchase products for humans.
Software could purchase services from other software.
That makes AI agent spending limits even more important because transaction volume could increase dramatically when machines can transact automatically.
How will AI agents be authorized to spend money?
The question how will AI agents be authorized to spend money is ultimately about delegated authority.
A human or business establishes the original permission. The payment infrastructure then needs to determine whether a particular transaction falls within that permission.
A future authorization flow could look something like this:
User instruction → agent identity → permission check → transaction evaluation → authentication → payment authorization
Each step answers a different question.
Did this user actually authorize the agent?
Is this the correct agent?
Is the purchase within the permitted amount?
Is the merchant allowed?
Does the transaction require additional confirmation?
Mastercard’s current Agent Pay framework, for example, emphasizes registered agents, traceability and verification of user intent.
This suggests that AI agent spending limits will probably work alongside identity and intent verification rather than replacing them.
Who is liable if an AI agent buys the wrong thing?
This may be the hardest problem.
Suppose an AI agent buys the wrong laptop, orders 500 items instead of five, or misunderstands a recurring subscription instruction.
Who is liable if an AI agent buys the wrong thing?
There is no single universal answer for every future agentic transaction. Responsibility can depend on the payment agreement, merchant terms, platform rules, consumer-protection law and how authorization was established.
That uncertainty is one reason traceability matters.
A payment system needs records showing:
- Who authorized the agent
- What permissions were granted
- What the agent was instructed to do
- Which merchant received the order
- What amount was authorized
- Whether additional confirmation was required
- Which system actually processed the payment
Clear AI agent spending limits can reduce the potential size of an error, but they cannot by themselves solve every liability question.
What happens when an AI makes hundreds of payments?
Now imagine an AI managing a company’s cloud infrastructure.
Instead of making one purchase, it could continuously buy computing resources, data services or API access.
Mastercard’s 2026 Agent Pay for Machines initiative explicitly describes a future in which AI agents and machines could transact continuously, including very small payments.
This is fundamentally different from human shopping.
Humans might make a few purchases in an hour. Machines can potentially execute transactions at machine speed.
That means AI agent spending limits may need to control not just individual transactions but also:
- Total spending
- Transaction frequency
- Merchant categories
- Time windows
- Cumulative exposure
- Automatic escalation rules
A ₹100 transaction might be harmless once. Ten thousand automated transactions could be something entirely different.
How to set budget controls for AI agents
For anyone eventually using autonomous payment agents, the principle behind how to set budget controls for AI agents is relatively simple: give the agent the minimum authority necessary for the task.
A sensible permission structure could include:
- Set a maximum transaction amount.
- Set a daily or monthly budget.
- Restrict the categories the agent can purchase.
- Require approval above a specific threshold.
- Use separate credentials where possible.
- Review transaction history regularly.
- Allow the permission to expire when the task ends.
The exact controls will depend on the financial service and AI platform.
The important principle is not maximum automation. It is controlled delegation.
The future of autonomous payments
Autonomous payments are already moving beyond research concepts. Visa, Mastercard, OpenAI, Stripe and other companies are building infrastructure intended to let AI agents participate in real transactions while preserving authentication and user controls.
The likely future is therefore not simply:
AI gets your credit card.
It is closer to:
AI receives a controlled financial identity with specific permissions.
That distinction matters.
An AI that can spend money but cannot be constrained is difficult to trust. An AI that can act quickly while operating inside clearly defined permissions is much more useful.
The AI agent spending limits of the future could therefore become as important as passwords, card security codes and two-factor authentication are today.
Conclusion
The question how will AI agents spend your money is really a question about trust.
Agentic commerce requires AI systems to move from recommending actions to actually performing them. That means payment infrastructure must know who the agent is, what the user authorized, how much it can spend and when it must ask for permission again.
AI agent spending limits are one part of that architecture.
Virtual credentials, payment tokens, authentication, trusted agent identities and protocols such as the Agentic Commerce Protocol and Machine Payments Protocol can provide additional layers.
The goal is not to prevent AI from spending money.
It is to make sure that when an AI does spend money, it spends only what it was authorized to spend, for the purpose it was authorized to pursue.
That may ultimately determine whether autonomous payments become a useful everyday tool—or a financial risk people are unwilling to delegate.
Frequently Asked Questions
What are AI agent spending limits?
AI agent spending limits are controls that restrict how much money an AI agent can spend, either per transaction, over a specific period, with particular merchants or under particular conditions.
How will AI agents be authorized to spend money?
AI agents can be given delegated permissions through payment tokens, authenticated identities, virtual credentials and transaction rules. Modern agentic-payment systems are being designed around user authorization and defined controls rather than unrestricted access to payment credentials.
Can AI agents use credit cards directly?
They can participate in card-based payment systems, but the emerging approach increasingly emphasizes tokens, delegated credentials and controlled authorization rather than simply giving an AI unrestricted access to a user’s primary card details. Visa is developing card-based support for machine payments, while OpenAI’s current Agentic Commerce Protocol uses payment tokens.
Who is liable if an AI agent buys the wrong thing?
Liability depends on the transaction structure, applicable law, merchant terms, payment provider and authorization arrangement. There is not one universal liability rule for all AI-agent purchases.
What is the Agentic Commerce Protocol?
The Agentic Commerce Protocol developed by OpenAI and Stripe is an open standard designed to let AI agents, people and businesses communicate and complete commerce transactions. It provides infrastructure for agent-mediated purchases while keeping merchants involved in payment and fulfillment.
What are virtual cards for AI?
Virtual cards for AI refer to the concept of using separate digital payment credentials for an AI agent instead of exposing a user’s primary payment credentials. Depending on the implementation, these credentials can potentially be subject to specific limits and controls.
What is the Machine Payments Protocol?
The Machine Payments Protocol, or MPP, is an open standard introduced by Stripe and Tempo for machine-to-machine payments. It is designed for automated transactions such as API calls, cloud resources and other machine services. Visa announced support for card-based MPP payments in 2026.
How can I control what an AI agent spends?
Use the narrowest permissions appropriate for the task: define transaction and periodic budgets, restrict merchants or categories, require approval for larger purchases, use separate credentials when available, and monitor the agent’s transaction history.
Explore more AI and technology insights in our [AI & Technology] section to learn how emerging AI systems are changing the way we work, pay and interact with technology.